- Taxes & Legal
Foreigners and Japanese Inheritance Tax: Property Ownership & Calculation Guide
Published On: November 12, 2026
Learn how Japanese inheritance tax applies to foreign property owners, including inheritance laws, tax calculations, deadlines, and filing requirements.
Table of Contents
Supervised By: Nobuyuki Ohki
Nobuyuki Ohki, Expert in Real Estate Taxation(CPA, Tax Accountant, Real Estate Transaction Specialist)
“What happens to my property in Japan if I die?”
“I reside outside of Japan. Is Japanese inheritance tax applicable to me?”
When a foreign national who owns real estate in Japan passes away, the transfer of ownership and the filing/payment of Japanese inheritance tax may be required under Japanese law.
Based on official guidelines from the National Tax Agency (NTA) of Japan, this article explains who inherits Japanese real estate and how inheritance tax is calculated.
If you would like to know more about the complete landscape of taxes related to real estate in Japan, please read the following article:
Japan Property Tax for Foreigners: Tax Rates, Costs & Rules Explained
1. Who Inherits Real Estate in Japan? (Applicable Law & Rights)
Determining who receives the property (transfer of ownership) depends on the governing law, or which country’s law applies.
- General Rule of Private International Law (Act on General Rules for Application of Laws, Article 36)
In principle, the inheritance is governed by the national law of the deceased (the law of their country of citizenship). (Source: Japanese Law Translation)
- Lex Loci Rei Sitae (also called lex situs) (Law of the Location of Property)
Some national laws state that foreign real estate is governed by the law of the country where the property is located (a concept known as renvoi). This is common in common law jurisdictions like the U.S. and the U.K. In such cases, the Japanese Civil Code (statutory heirs and wills) applies to real estate located in Japan.
- Presence of a Will
If a legally valid will exists, ownership is transferred according to the terms of the will, regardless of nationality.
2. Scope of Japanese Inheritance Tax
When a foreign national passes away, the extent of property subject to Japanese inheritance tax (taxable assets) depends on the residency history and nationality of both the deceased (decedent) and the person receiving the property (heir).
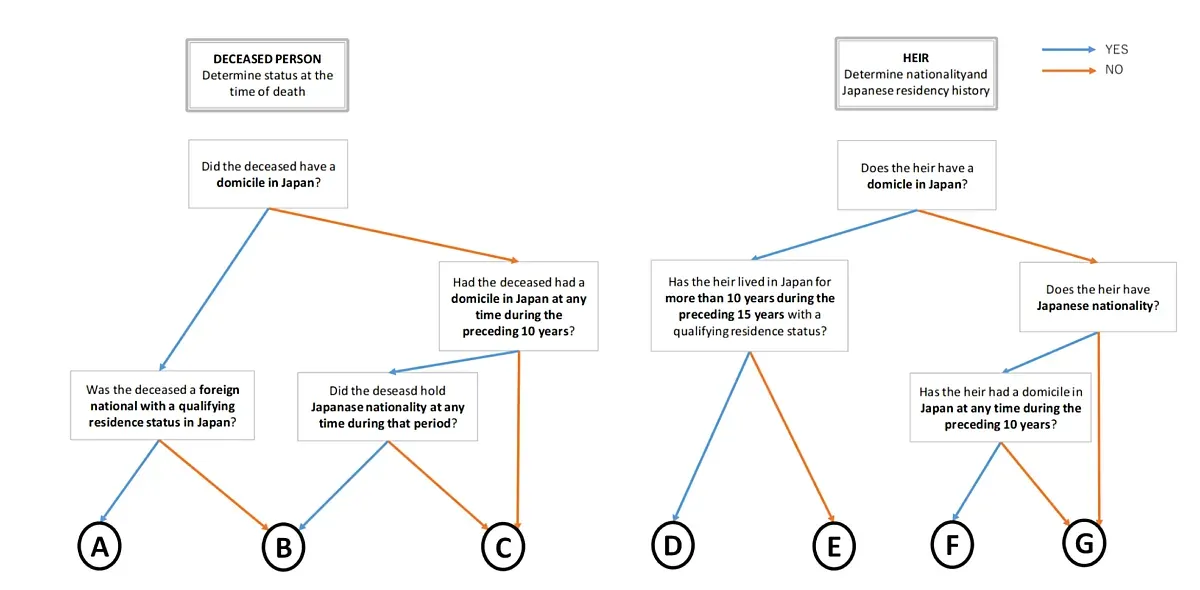
Taxable Assets
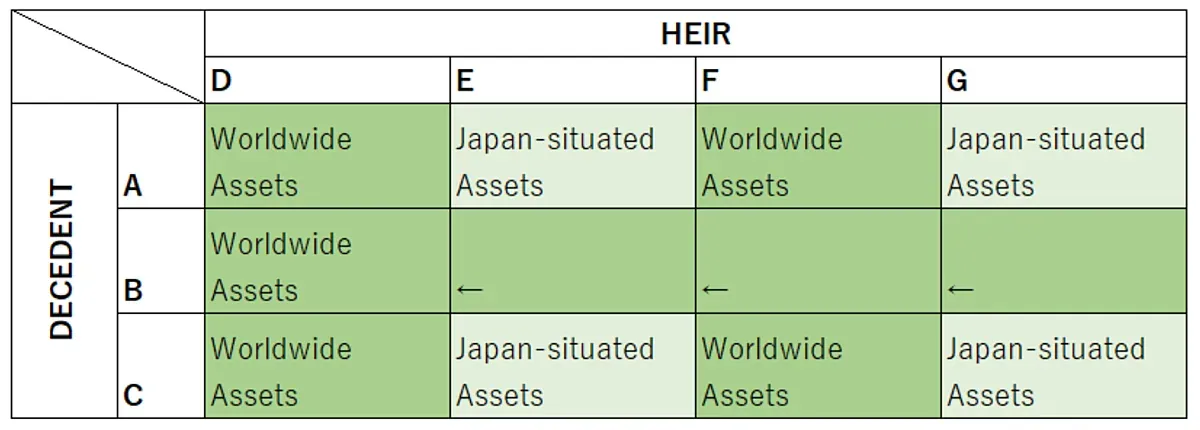
(Source: Created by PropertyAccess based on When an heir resides abroad, National Tax Agency)
The key takeaway here is that even if both the deceased and the heir live abroad and hold foreign nationality, real estate located in Japan is basically subject to Japanese inheritance tax.
3. How Japanese Inheritance Tax Is Calculated
Japanese inheritance tax is calculated on the remaining value of the estate after subtracting the Basic Deduction (tax-exempt threshold).
Step 1: Property Valuation
Real estate is evaluated using standards set by the National Tax Agency, rather than actual market transaction prices.
- Land: Evaluated based on the Roadside Value (Rosenka), which is generally around 70%–80% of market value.
- Buildings: Evaluated based on the Property Tax (Fixed Asset Tax) Assessment Value, which is generally around 50%–60% of market value.
A major revision to the valuation of real estate for inheritance tax purposes is scheduled to take effect in January 2027.
From January 2027, rental properties acquired within five years prior to inheritance will, in principle, be valued at Valuation = Acquisition Price × Land Price Change Rate × 80%.
This is expected to result in higher taxable values than under the current valuation rules.
Step 2: Subtracting the Basic Deduction
The Basic Deduction is subtracted from the total assessed value of the estate:
Basic Deduction = JPY 30,000,000 + (JPY 6,000,000 x Number of Statutory Heirs)
For example,
if the heirs are a spouse and 2 children (3 statutory heirs in total):
JPY 30,000,000 + (JPY 6,000,000 x 3) = JPY 48,000,000
If the total assessed property value is JPY 48,000,000 or less, no inheritance tax is owed, and no tax return needs to be filed.
Step 3: Calculating and Allocating Tax
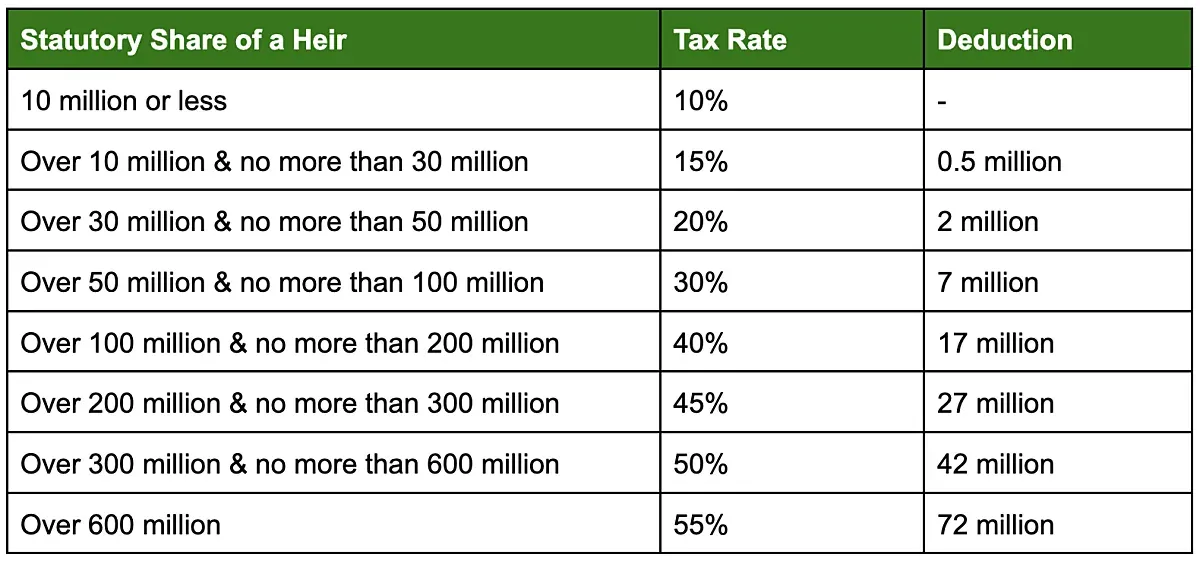
If the total value exceeds the Basic Deduction, the taxable amount is tentatively divided among statutory heirs based on Japanese statutory share ratios.
Progressive tax rates ranging from 10% to 55% are applied to determine the total tax pool, which is then allocated to each heir based on the proportion of assets they actually receive.
[Japanese Inheritance Tax Rate]
For example,
If the taxable amount of inheritance after subtracting the basic reduction is JPY 152 million for statutory heirs of wife and 2 children,
The statutory share will be:
Wife ½ = JPY 76,000,000
Child 1 ¼ = JPY 38,000,000
Child 2 ¼ = JPY 38,000,000
The tax amount will be:
Wife = JPY 76,000,000 x 30% - 7,000,000 = 15,800,000
Child 1 = JPY 38,000,000 x 20% - 2,000,000 = 5,600,000
Child 2 = JPY 38,000,000 x 20% - 2,000,000 = 5,600,000
—-------------
17,000,000
If they are dividing the inheritance in a way different from the statutory share ratios, this total tax amount 17,000,000 will be allocated to each heir based on the proportion of assets they actually receive.
4. Essential Tips for Foreign Nationals
- Strict 10-Month Deadline
The inheritance tax return must be filed, and the tax due must be paid, with the tax office having jurisdiction over the decedent’s address at the time of death within 10 months from the day following the day on which the heir becomes aware of the decedent’s death.
- Appointing a Tax Agent (Nōzei Kanri-nin)
Because heirs residing abroad cannot easily communicate with or handle procedures directly with Japanese tax offices, they must appoint a resident of Japan (such as a licensed tax attorney or legal professional) as their Tax Agent and register them with the tax office.
Any individual or firm can act as your tax agent, as long as they reside in Japan.The form to register a tax agent can be found on the NTA’s website.
- Foreign Tax Credit (Avoiding Double Taxation)
If the same real estate is subject to inheritance or estate taxes in the heir’s home country, a Foreign Tax Credit may be claimed in Japan or the home country to avoid double taxation.
There is no need to be overly concerned about Japanese inheritance tax.
However, if you are considering investing in Japanese real estate and would like professional advice, please feel free to contact Property Access.
We can arrange a consultation with our partner tax accountant.
Our team of seasoned professionals at PropertyAccess is dedicated to helping you navigate Japan’s real estate market with confidence.
With deep local knowledge and a commitment to personalized service, our experts are here to guide you every step of the way.
Book a Free Consultation Session with Our Team!